
Welfare Stamp On Vakalat Is Not A Toll On Right To Practise: Telangana High Court Upholds Mandatory Advocates Welfare Fund Levy
The Court dismissed an advocate’s challenge to Sections 12 and 12A of the Telangana Advocates Welfare Fund Act, 1987, holding that the State was competent to enact the levy under Entries 23 and 26 of the Concurrent List.
The Telangana High Court has held that the mandatory welfare fund stamp affixed to every Vakalat under Section 12 of the Telangana Advocates Welfare Fund Act, 1987 is not a toll on the right to practise and does not amount to an unreasonable restriction under Article 19(1)(g) of the Constitution of India. It held that the requirement is procedural and attaches only to the manner of filing, and that a Registry declining a Vakalat without the stamp merely complies with the statute.
On the doctrine of pith and substance, the Court held that the Act is a social welfare measure for the legal profession, traceable to Entries 23 and 26 of List III. Its effect on Entry 78 of List I, which covers the right to practise before High Courts, is only incidental. The Court rejected the pleas of repugnancy and colourable legislation and the argument that the levy was invalid for being neither a tax nor a fee.
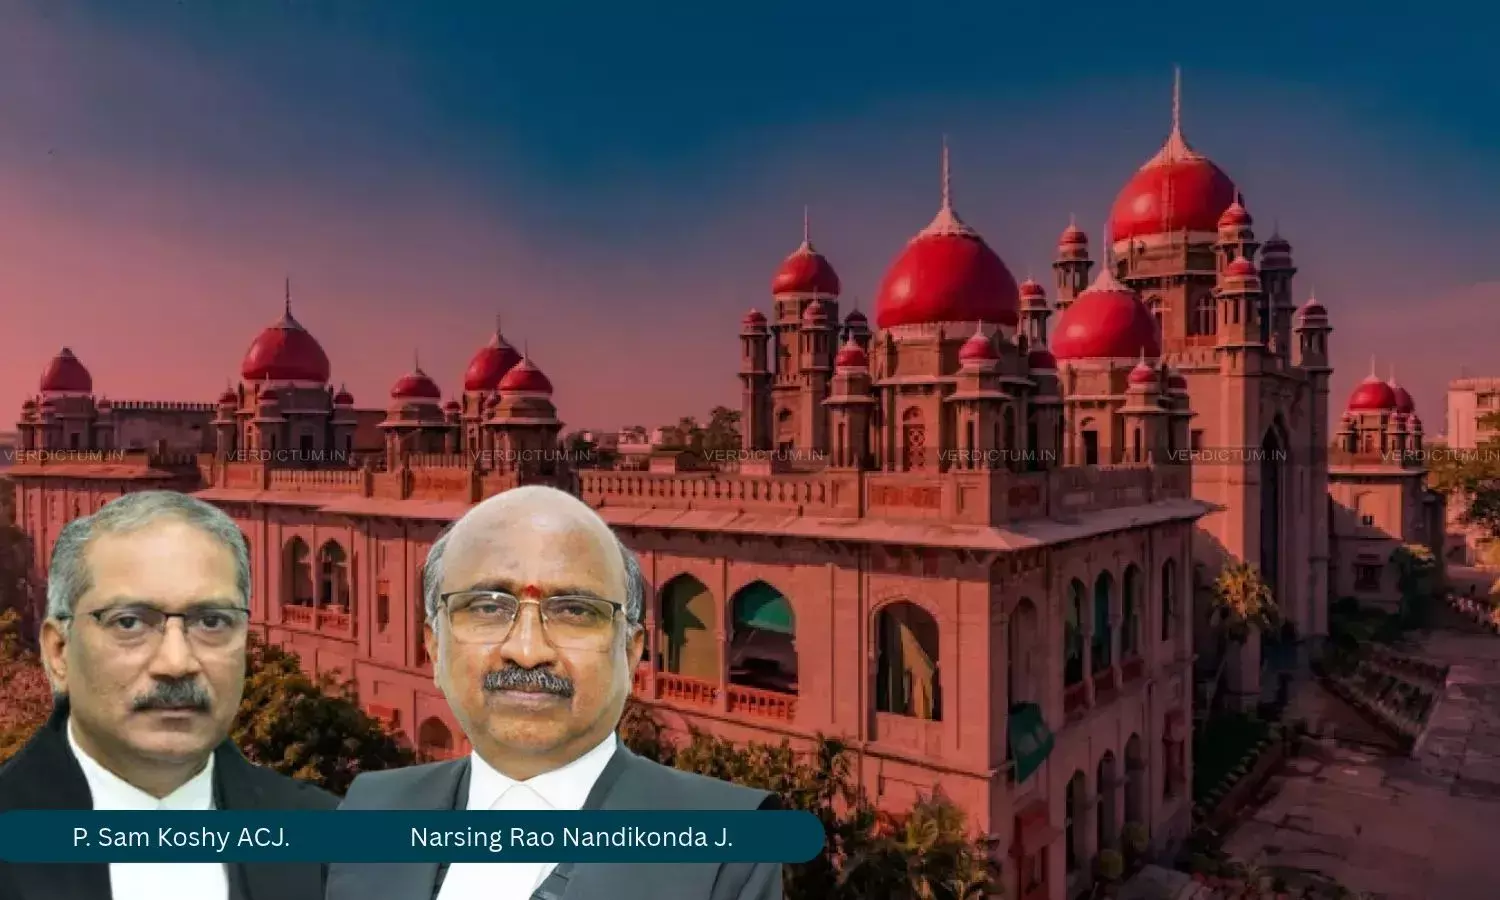
A Division Bench of Acting Chief Justice P. Sam Koshy and Justice Narsing Rao Nandikonda observed, “…The sum that is asked of every Advocate when a Vakalat is filed is slight. It is not a toll on the right to practise. It is the thread by which a profession ties together those who are fortunate with those who fall into hardship. A fund of this kind is built from many small contributions. No individual contribution is great but together they form a safety net that no one could build alone. An individual objection to a modest sum must yield where the sum is collected under valid law and applied to a larger interest in which the contributor himself shares. The law protects the individual from arbitrary exactions. It does not exempt the individual from contributing towards a shared and lawful purpose. Hence, the amounts collected by the State under the Act are legal and warrant no interference by this Court”.
In the matter, the petitioner appeared in-person while D. Surender Kumar, AGP appeared for the respondent.
“…Article 19(1)(g) guarantees the right to practise any profession. The right is subject to reasonable restrictions in the interest of the general public under Article 19(6). The welfare stamp does not prevent the petitioner from practising. It does not limit the number of cases he may take up. It is a small recurring contribution that supports a fund for Advocates who face illness or old age or other hardship and for the clerks who assist them. A contribution of that kind towards the welfare of the profession is a reasonable burden. We cannot say that it amounts to an unreasonable restriction. The Registry in declining to accept a Vakalat without the stamp, acts in compliance with the statute and exercises no discretion of its own. The requirement is procedural and attaches only to the manner of filing”, the Bench noted further.
The petitioner, an advocate appearing in person, challenged Section 12 of the Act, which requires a welfare fund stamp on every Vakalat. He also challenged Section 12A, which distributes the proceeds between the Advocates Welfare Fund and the Advocates Clerks Welfare Fund. The stamp value was revised over successive amendments, to ₹100 in 2018 and to ₹250 in 2025.
The petitioner contended that the subject fell exclusively within Entry 78 of List I and was repugnant to Sections 6 and 7 of the Advocates Act, 1961 and the Advocates Welfare Fund Act, 2001. He argued that the amendments lacked fresh Presidential assent and that the levy violated Articles 14, 19(1)(c), 19(1)(g) and 31C. He also argued that the proceeds were not credited to the State Exchequer under Article 283. The State contended that the levy was a statutory welfare fee credited to a statutory committee.
The Bench held that the Advocates Act authorises certain welfare funds but does not prohibit a State from mandating a compulsory contribution. It observed that the silence of Parliament in the 2001 Act cannot be read as a negative command.
On finding no repugnancy, it held that Article 254(2) was not attracted and the amendments needed no fresh assent. It held that Article 31C is a protective provision, not a condition of validity. It also held that no one is compelled to join an association, and that the sharing ratio is a matter of legislative policy. On Article 283, it held that the proceeds are impressed with a trust for a statutory purpose and do not become State revenue. It added that court fee and the welfare stamp serve different purposes. It noted that Section 38 of the 2001 Act expressly saves notified State fund Acts.
Cause Title: Vijay Gopal v. State of Telangana & Ors. (Writ Petition No. 13352 of 2025)
Appearances:
Petitioner: In person
Respondent: D. Surender Kumar, Assistant Government Pleader.