
Fixing Solar Power System On Civil Foundation For Stability Does Not By Itself Make It Immovable Property: Supreme Court
The Court held that the supply and installation of Solar Power Generating systems is not a “works contract” under the CGST Act, and that the 70:30 goods-services ratio for the period before January 1, 2019 was only an option, not a mandate.
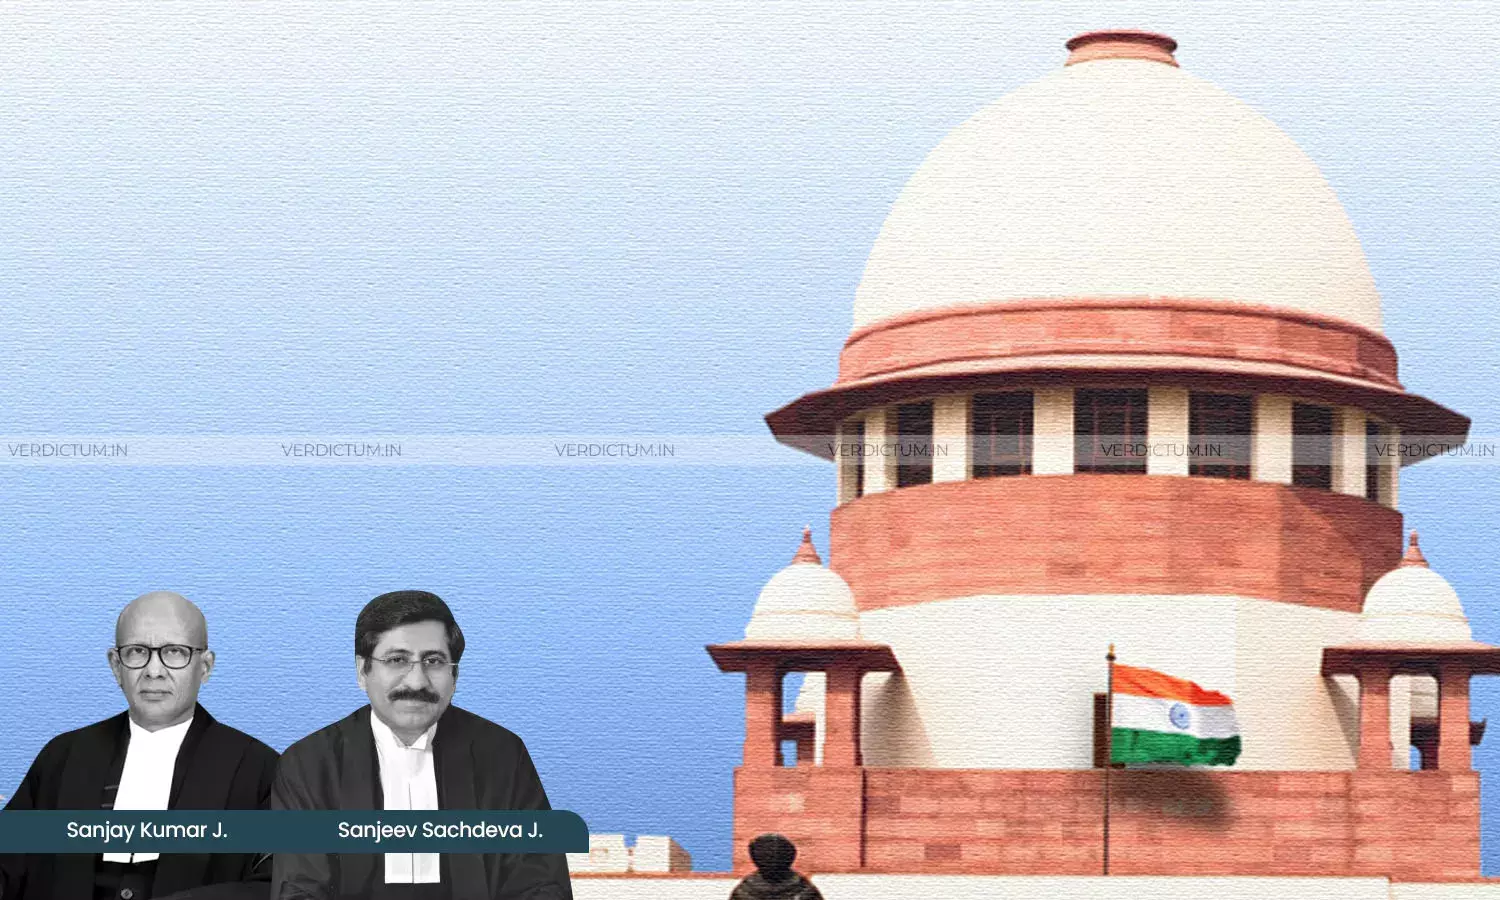
The Supreme Court has held that the fact that a Solar Power Generating (SPG) system has to be fixed on a civil foundation for stability and to ensure proper functioning does not, by itself, convert it into immovable property. Setting aside a GST demand of about ₹53 crore on Sterling and Wilson Pvt. Ltd., the Court held that a contract for supply and installation of such systems does not become a works contract merely because it includes civil works.
The Court explained that every composite supply under Section 2(30) of the CGST Act does not qualify as a works contract under Section 2(119), which requires the contract to relate to an activity pertaining to immovable property as an end product. It also held that Circular No. 163/19/2021-GST gave assessees only an option to pay tax in the 70:30 ratio for July 1, 2017 to December 31, 2018, and that treating it as mandatory was patently erroneous. It further held that extended limitation under Section 74 was completely unsustainable for that period.
A Division Bench of Justice Sanjay Kumar and Justice Sanjeev Sachdeva observed, “…As rightly pointed out by the Andhra Pradesh High Court, every ‘composite supply’, in terms of Section 2(30) of the CGST Act, would not qualify as a ‘works contract’ under Section 2(119) thereof. To do so, the contract in question must relate to some activity pertaining to immovable property as an end product. The fact that a SPG system has to be fixed on a civil foundation for stability and to ensure proper functioning would not, by itself, convert it into immovable property…Applying the tests adumbrated by this Court, when a SPG system can be easily detached from the foundation and used elsewhere, it is impossible to accept the Revenue’s contention that a SPG system must be treated as immovable property, so as to bring the contract for supply and installation thereof within the ambit of a works contract.”.
Senior Advocates Arvind P. Datar, and Prakash Shah appeared for the appellant while Advocate Karan Lahiri appeared for the respondent.
The appellant, M/s Sterling and Wilson Pvt. Ltd., installs solar power systems on a turnkey EPC basis. For July 1, 2017 to December 31, 2018, it paid tax at 5% on the entire contract value, treating the supply as goods under Serial No. 234 of Notification No. 1/2017-Central Tax (Rate).
The Joint Commissioner, CGST, Thane, held the supply to be a composite supply and a works contract, as a solar plant was immovable property. He applied the 70:30 ratio at 5% and 18%, and invoked extended limitation. The order of January 17, 2025 and the Summary Order of January 24, 2025 demanded CGST of ₹13.33 crore with equal penalty, with SGST and its penalty bringing the total to ₹53.35 crore.
The Bombay High Court dismissed the appellant’s writ petition on July 28, 2025, on the ground of an alternate remedy, without noticing that two orders were challenged. The Supreme Court stayed the order on August 25, 2025.
The Court held that the alternate remedy bar is “not a straitjacketed formula” and that arguable points warranted consideration. It then decided the matter itself, as it had been argued at length and the Andhra Pradesh High Court had adjudicated the issue.
On the merits, it held that the SPG system can be easily detached and used elsewhere, and that attachment benefits the system and not the foundation. It endorsed the Andhra Pradesh High Court’s view in the appellant’s own case, which the Revenue did not challenge. It also held that the later substitution of Serial No. 234 by Serial No. 201A, replacing “system” with “generator”, cannot apply retrospectively.
Cause Title: M/s. Sterling and Wilson Pvt. Ltd. v. Union of India & Ors. (Neutral Citation: 2026 INSC 1222)
Appearances:
Appellant: Arvind P. Datar, Sr. Adv., Prakash Shah, Sr. Adv., Mihir Mehta, Vishnu Kant- 2998, AOR Rajnandini, Sarthak Singh, Ratnesh Kumar, Shikha Bharti, Advocates.
Respondent: N. Venkataraman, ASG (N/P), Karan Lahiri, Gurmeet Singh Makker- 2357, AOR, Aaditya Dixit, Digvijay Dam, Raman Yadav, Advocates.