
Electricity Subsidy Tied to Power Charges Received Under Govt Scheme Is Revenue Receipt: Supreme Court
The Supreme Court was considering an appeal concerning the nature of the electricity subsidy received by the assessee from the Government of Pondicherry.
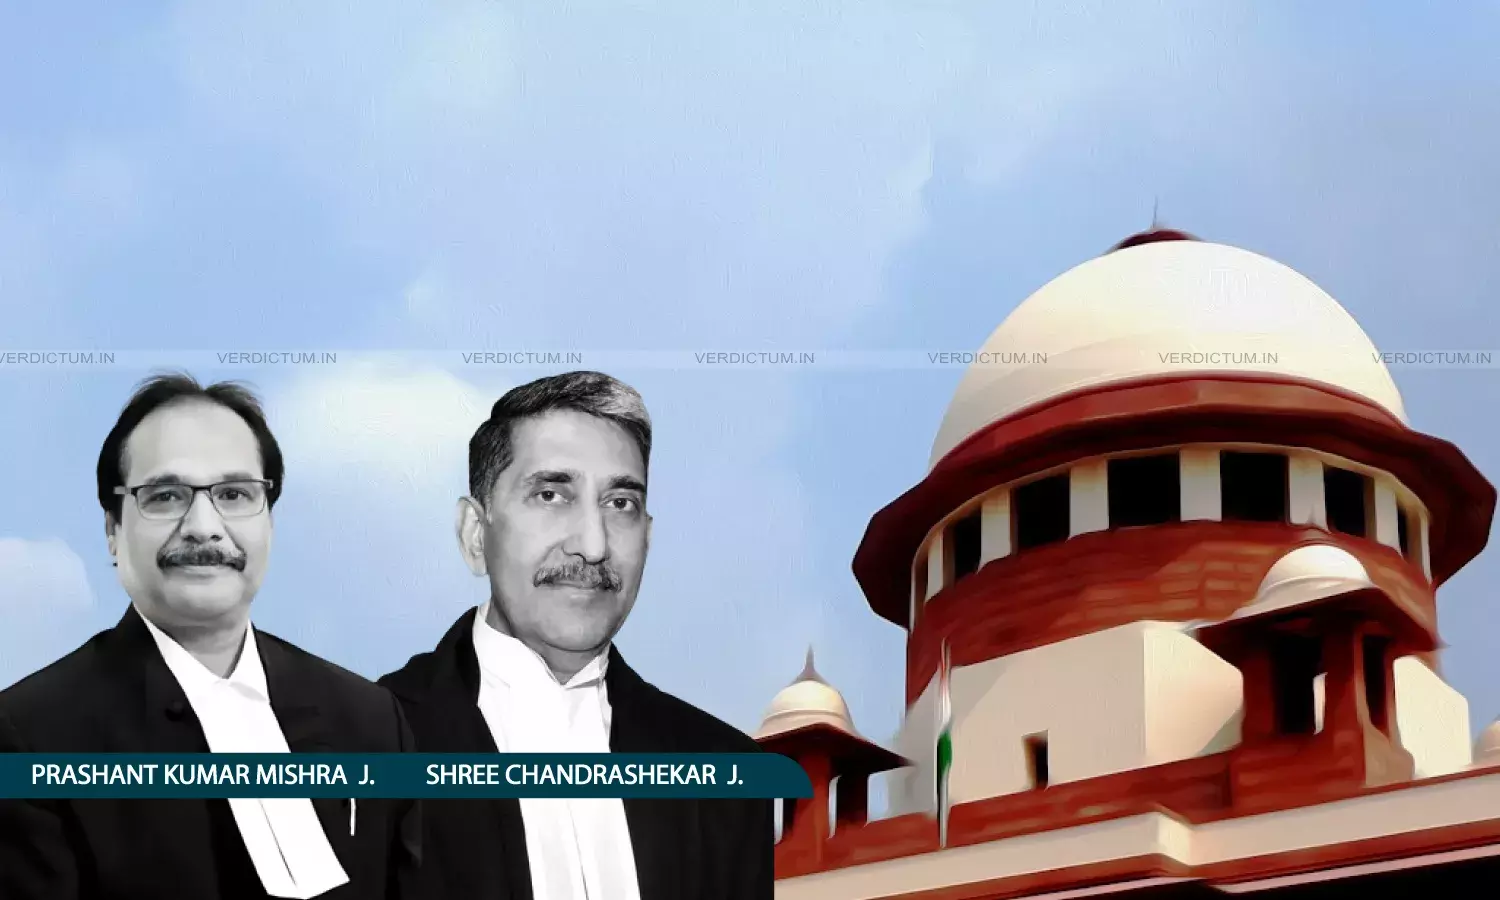
Justice Prashant Kumar Mishra, Justice Shree Chandrashekhar, Supreme Court
The Supreme Court has affirmed the view of the Assessing Officer as well as the Income Tax Appellate Tribunal in appreciating the nature of electricity subsidy tied to power charges received under a Government scheme as a revenue receipt.
The Apex Court was considering an appeal concerning the nature of the electricity subsidy of Rs 16,20,745 received by the appellant-assessee, M/s. Mepco Industries Ltd., from the Government of Pondicherry for the Assessment Year 1997-98.
The Division Bench of Justice Prashant Kumar Mishra and Justice Shree Chandrashekhar held, “In light of the above analysis, we find that the Assessing Officer, CIT (Appeals) and ITAT had correctly appreciated the nature of subsidy as a revenue receipt and as being given after the establishment of the industrial unit and commencement of production; that it was calculated with reference to power charges; that it reduced the cost of electricity consumed by the appellant-assessee; and that it was not shown to be a contribution towards bringing any new capital asset into existence.”
Advocate Tushar Jarwal represented the Appellant while Additional Solicitor General N Venkataraman represented the Respondent.
Factual Background
The appellant is a limited company engaged in the manufacture of potassium chlorate. For the relevant assessment year, it received the aforesaid amount as electricity subsidy and treated the same as a capital receipt. The subsidy was granted under the Scheme of Power Subsidy of the Government of Pondicherry, which had been in operation since November 27, 1975. The rate of subsidy was 33⅓% of the power charges for the first three years, 20% for the fourth year and 10% for the fifth year, subject to the applicable ceiling.
The appellant's case was that the scheme was intended to encourage the establishment of new industries in backward areas, whereas on the other hand, the Revenue Authorities had treated the subsidy as assistance towards the cost of power consumed in the course of the existing business. The appellant filed its return of income. In the return, it claimed the electricity subsidy of Rs 16,20,745 as a capital receipt not liable to tax. The Assessing Officer treated the subsidy as a revenue receipt and included the amount of Rs 16,20,745 in the taxable income. In doing so, it was held that the subsidy was given towards revenue expenditure and treated it as revenue in character. Aggrieved by the assessment, the appellant approached the Commissioner of Income Tax (Appeals), but the appeal was dismissed.
The appeal before the Income Tax Appellate Tribunal, Chennai, also failed. Aggrieved, the appellant preferred an appeal before the Madras High Court and the same was dismissed. The High Court held the receipt to be revenue in character, thereby taxable under the IT Act. Aggrieved thereby, the appellant approached the Apex Court.
Reasoning
On a perusal of the scheme in question, the Bench noted that the benefit was calculated as a specified percentage of the actual energy charges, and it was available for a limited period commencing with production, and its immediate and direct effect was to reduce the electricity cost incurred in the manufacturing process. “The scheme does not require the subsidy to be applied towards acquisition of plant or machinery, construction of the factory, repayment of a capital borrowing, or creation of any other capital asset. The record before us does not disclose that the amount received by the appellant was earmarked for any such capital purpose. On the contrary, the very basis of quantification is the expenditure on power consumed in production”, it added.
The Bench further noted that the scheme made the commencement of production the point from which the five-year subsidy period runs, and the amount thereafter depends upon the actual energy charges incurred. According to the Bench, the fact that the subsidy was released only after commencement of production could not be regarded as the sole reason for treating it as revenue.
The Bench explained, “We are also unable to accept the contention of the appellant that the expression “to foster the growth of industries” occurring in the subsidy scheme, by itself, determines the character of the receipt. The “purpose test” cannot be applied by isolating one general object clause while disregarding the operative provisions of the scheme. The scheme must be read as a whole, and when so read, the general object of industrial development is implemented through a specific subsidy on power charges, calculated with reference to actual energy charges and available only for a defined period after production commences. It is this immediate and operative purpose of the financial assistance that determines its character in the hands of the assessee.”
According to the Bench, the next aspect that went against the appellant-assessee was that the subsidy did not lose its revenue character merely because reduction in electricity expenditure might leave more funds available with the assessee for its business. “The relevant inquiry is whether the Government intended to make a contribution towards the capital structure or capital assets of the undertaking. A perusal of the record would reveal no such feature in the scheme. Rather, the subsidy substitutes for, or reduces, a part of an expense which the assessee incurs in the ordinary course of manufacturing operations”, it stated.
Thus, holding that the Assessing Officer, CIT (Appeals) and ITAT had correctly appreciated the nature of subsidy as a revenue receipt, the Bench dismissed the appeal.
Cause Title: M/S. MEPCO Industries Ltd. v. Commissioner of Income Tax, Madurai (Neutral Citation: 2026 INSC 1090)
Appearance
Appellant: Advocate Tushar Jarwal, AOR Radha Rangaswamy, Advcoates Ranjeeta Rohatgi, Shrika Gautam
Respondent: Addl. Solicitor General N Venkataraman, Sr. Advocate Arijit Prasad, AOR Sudarshan Lamba, Advocates Chandrashekhara Bharathi, Gaurav Arya, Gargi Khanna, Rashmi Malhotra, Bhuvan Kapoor