
Supreme Court To Examine Whether Food Safety Act Overrides Customs Act On Sampling And Testing Of Imported Food
Noting that the goods in question are areca nuts, a perishable commodity, the Court issued notice on a plea against a Calcutta High Court order.
The Supreme Court has issued notice on a special leave petition raising the question of whether the provisions of Sections 25 and 47 of the Food Safety and Standards Act, 2006 would override the provisions of the Customs Act, 1962, particularly Sections 110 and 144, in respect of the sampling and testing of imported food articles.
The petition was filed challenging an order of the Calcutta High Court which held that the two enactments operate in distinct, concurrent and non-conflicting legislative fields, and had upheld the sampling of an areca nut consignment by the Directorate of Revenue Intelligence (DRI) and Customs authorities.
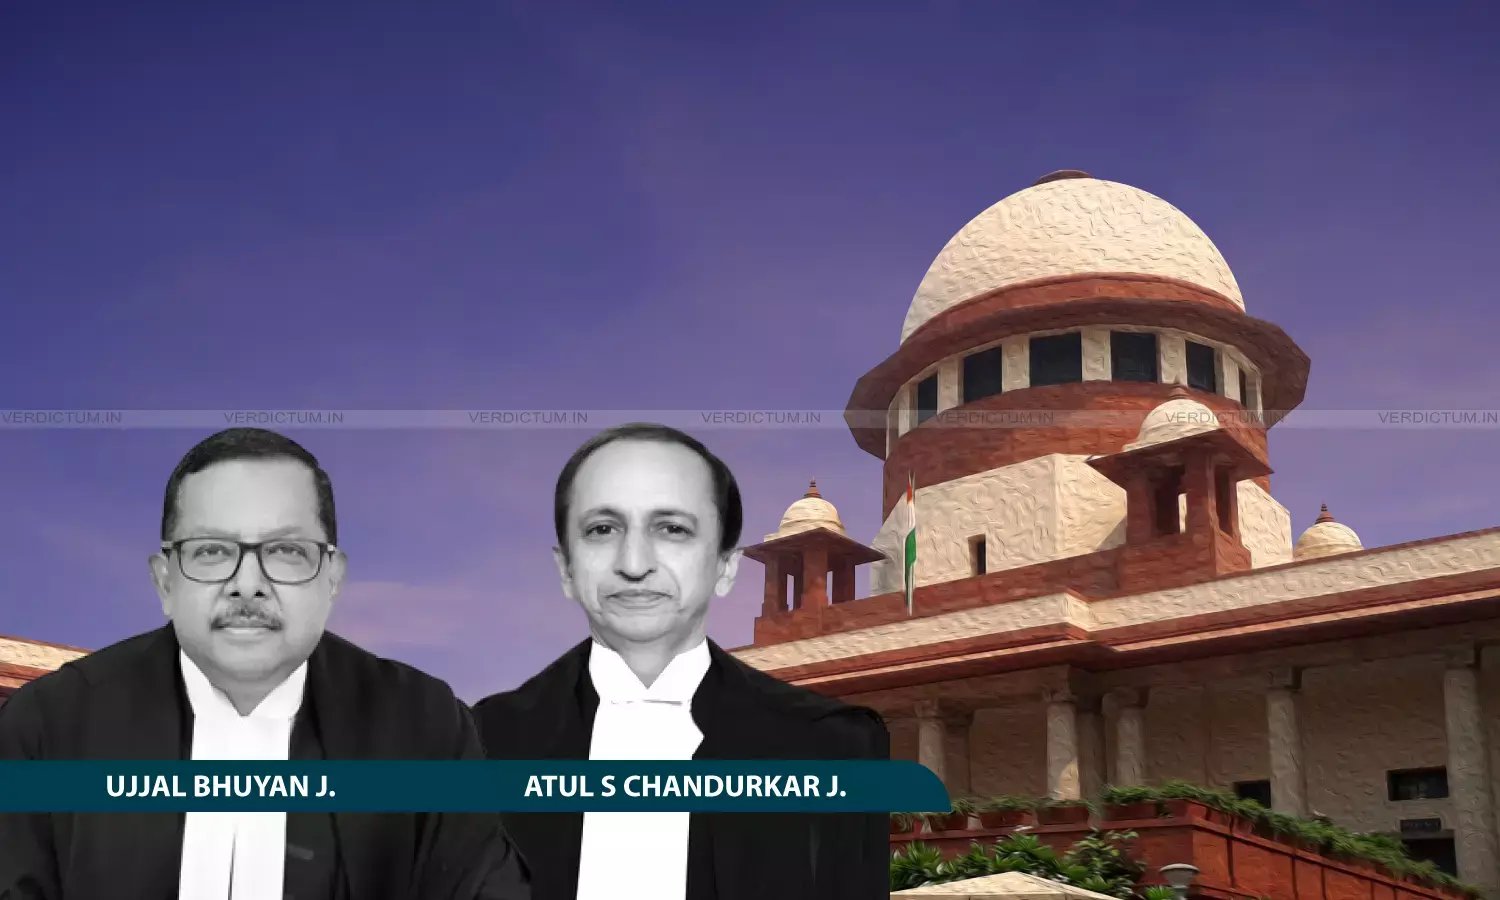
The Bench of Justice Ujjal Bhuyan and Justice Atul S. Chandurkar ordered, “This petition raises an important issue of considerable significance. The issue is whether provisions of Sections 25 and 47 of the Food Safety and Standards Act, 2006 would override the provisions of the Customs Act, 1962, more particularly Sections 110 and 144 thereof, specifically in respect of sampling and testing of imported food articles.”
Senior Advocate Siddharth Dave appeared for the Petitioner.
Background
The importer had procured a consignment of foreign-origin areca nuts from Belawan Port, Indonesia, and filed a Bill of Entry at Inland Container Depot (ICD) Durgapur declaring the cargo as “Roasted Areca Nuts” under CTH 20081991. The consignment comprised three containers weighing 84.48 metric tons, with an assessable value of Rs.1,12,21,197/-.
Based on specific intelligence that prohibited dried areca nuts (CTH 080280) had been misdeclared as roasted areca nuts to bypass DGFT Minimum Import Price (MIP) conditions and CBIC Tariff Values, the DRI Kolkata Zonal Unit issued an Alert Notice holding the consignment and preventing its routing to the Food Import Clearance System (FICS) on ICEGATE.
Samples drawn under Section 144 of the Customs Act were sent to the National Food Laboratory (NFL), Kolkata, which declared them unsafe under Section 3(1)(zz) of the FSS Act due to mould, insect infestation and excessive aflatoxin content. Customs then seized the containers under Section 110(1) of the Customs Act. On the importer’s request, samples were re-tested at the Central Revenues Control Laboratory (CRCL), New Delhi, which confirmed that the cargo was misdeclared and unfit for human consumption.
The importer challenged the Customs sampling and seizure, seeking fresh sampling strictly through FSSAI-authorised officers under Section 47(5) of the FSS Act. A Single Judge of the High Court allowed the writ petitions. The Single Judge held FSSAI officers to be the sole competent authority to draw samples from imported food articles, declared the Customs sampling illegal and void, quashed the NFL and CRCL reports and ordered fresh sampling.
Impugned High Court Judgment
In intra-court appeals filed by the DRI and the Commissioner of Customs (Preventive), Kolkata, the Division Bench set aside the Single Judge’s order. It held that Section 144 of the Customs Act is plenary and is not curtailed by the physical or edible description of the cargo, and that food items do not lose their identity as imported goods or enjoy immunity from Customs inspection or sampling.
The High Court held that determining the true identity and tariff classification of an imported commodity is an antecedent statutory requirement under the Customs Tariff Act, 1975, while the function of FSSAI is limited to certifying whether the item is safe for human consumption. It observed, “Food safety legislation cannot be invoked as a shield to oust or displace antecedent threshold investigations conducted by Customs authorities into tariff classification and fiscal fraud.”
The High Court further held that Section 89 of the FSS Act gives overriding effect only in respect of direct inconsistencies concerning food safety standards. It also held that FSSAI’s exclusive sampling procedure under Regulation 5 of the FSS (Import) Regulations, 2017 commences only after a Bill of Entry is routed to FICS, and that executive instructions such as CBIC Instruction No. 04/2026-Customs cannot curtail statutory powers under Section 144.
Holding that challenges to sampling, testing methodology and report admissibility are to be adjudicated in the show cause notice proceedings under Sections 122 and 124 of the Customs Act, the High Court vacated the Single Judge’s directions for fresh sampling, videography, fixed laboratory timelines, cargo release and demurrage waivers. It directed the Customs authorities to proceed with the show cause notice adjudication in accordance with law.
Cause Title: M/s Credence International v. Additional Director General, Directorate of Revenue Intelligence, Kolkata & Ors. [SLP (C) No. 38953/2026]
Appearances:
Petitioner: Sr. Adv. Siddharth Dave, AOR Shashank Kumar Vemulakonda, Adv. Harsh Gattani, Adv. Tanisha Kaushal