
Punjab & Haryana HC Orders Interim Release Of Arrested CGST Assessee; Slams Department For 'Brazen Highhandedness' And Overreaching Court Orders
The Court ruled that arresting an assessee present under court orders without informing the bench prima facie violates Article 21 and overreaches judicial proceedings.
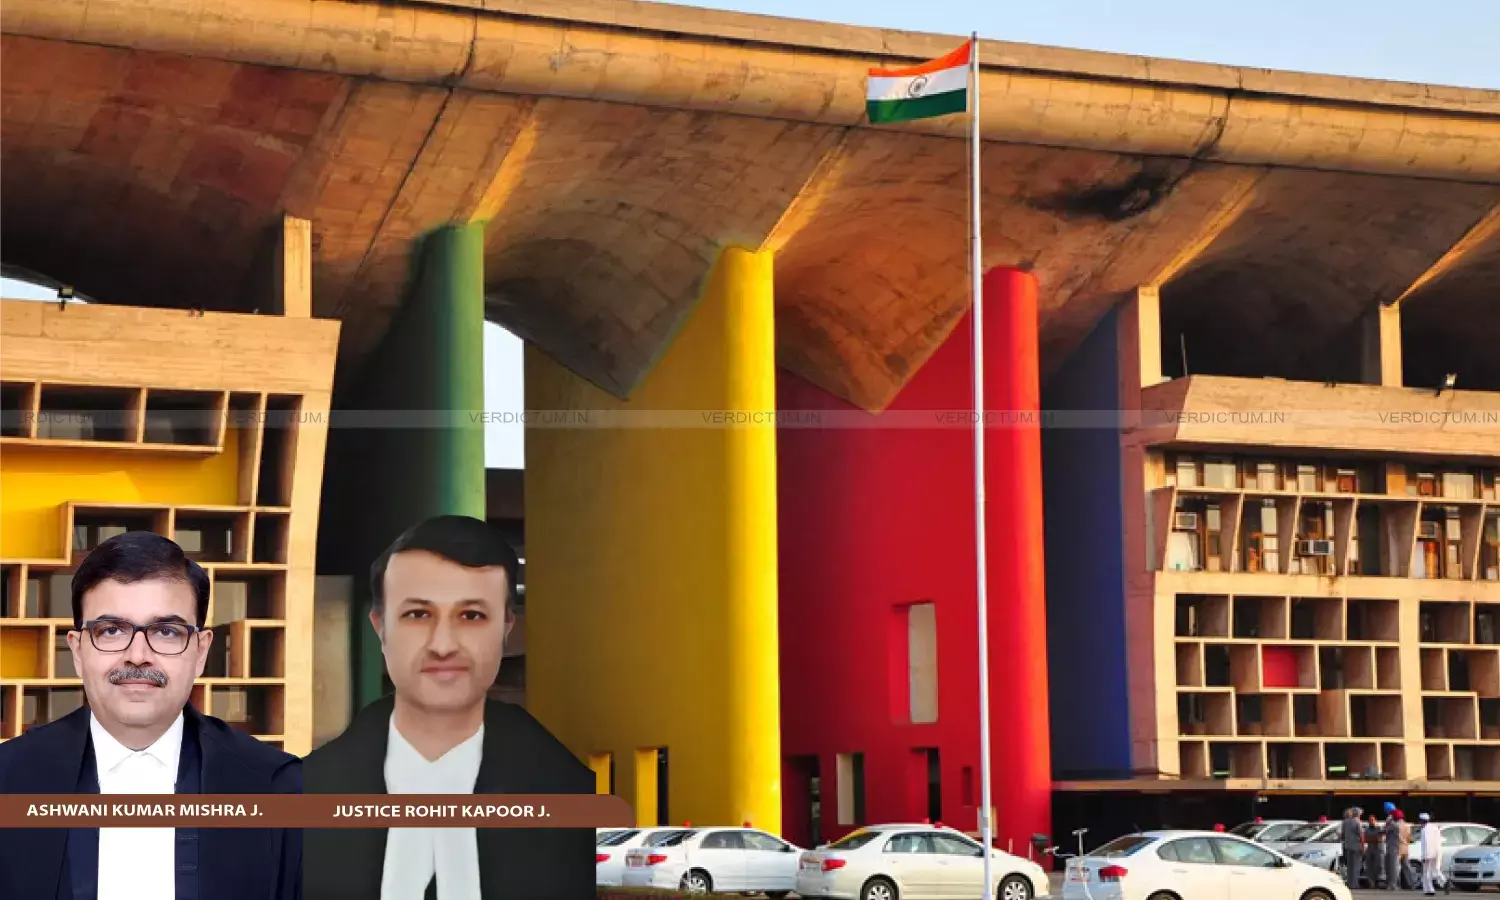
Justice Ashwani Kumar Mishra, Justice Rohit Kapoor, Punjab and Haryana High Court
The Punjab & Haryana High Court has granted immediate interim release of a GST assessee who was arrested by CGST authorities after appearing before them pursuant to court directions and was willing to cooperate with the investigation.
The Court reprimanded the revenue department for its "brazen act of highhandedness" and violation of Article 21, noting that detaining the petitioner through the night and suppressing judicial orders in arrest documents was a prima facie attempt to overreach pending court proceedings.
Consequently, the bench personally impleaded the concerned senior officers to show cause for their conduct.
The Division Bench of Chief Justice Ashwani Kumar Mishra and Justice Rohit Kapoor observed, "Prima-facie we find the reasons for authorizing petitioner’s arrest to be wholly misplaced inasmuch as the petitioner was already present before the authorities with all records and was willing to cooperate with the investigation under the orders of this Court. This Court was otherwise seized of the matter. The authorization for arrest neither records the orders passed by this Court nor the fact that the petitioner has already appeared along with records to facilitate investigation in the matter. The routine manner in which the authorization to arrest the petitioner is issued by the department leaves much to be desired. We, otherwise, find the action of the respondents to be an attempt to overreaching the proceedings of the Court."
Senior Advocate N.S. Boparai appeared for the Petitioner, while Senior Standing Counsel Sourabh Goel appeared for the Respondents
Brief Facts of the Case
A petition was filed seeking directions to the Union of India and others to quash the arrest memo and authorization for arrest in a case. The Petitioner also previously filed a writ petition challenging the provisional attachment of his bank account by GST authorities.
During the hearing of that writ petition, it was alleged by the Respondents that the Petitioner was not cooperating with the GST authorities in the investigation.
The High Court had directed him to appear before the adjudicating GST authorities at 11:00 AM on September 23, 2026, to furnish requested documents, and directed the revenue to report the status of the matter on September 29, 2026.
In compliance with the order of the court, the petitioner appeared at the GST office at 11:00 AM on September 23, 2026. However, authorities summoned him at 12:05 PM on the same day and kept him detained throughout the day and night.
The GST authorities recorded his arrest at 4:45 AM on September 24, 2026. The petitioner pointed out irregularities, including an ante-timed Document Identification Number.
Hence, the petitioner filed the present writ petition, alleging that the department's high-handed actions violated Article 21 of the Constitution and overreached the court's pending proceedings.
Submissions of the Parties
The Petitioner submitted that he appeared before the authorities in terms of directions issued by this Court and also produced all documents which had been desired by the authorities.
The petitioner said that he was made to sit in the office of the respondent the whole day and night, and the time of arrest has been shown as 4:45 am the next morning. The authorization of arrest does not make any reference to the order passed by the Court in that plea, pursuant to which the petitioner had appeared before the authorities.
On the contrary, the Revenue stated that since there was no order staying the arrest of the petitioner and his anticipatory bail was already rejected, the action of the respondents in arresting the petitioner suffers from no illegality.
Observations/Findings of the Court
When the matter was taken up in the pre-lunch session, the Court observed, "The least that was expected on the part of the authorities was to have apprised the Court of any development and to proceed against the petitioner with the leave of the Court particularly when the matter was pending consideration and was specifically listed for 29.09.2026 for the authorities to report the status of the investigation. The undue hot haste which has been shown in detaining the petitioner at 11:00 am on 23.09.2026 and arrested him on the next date at 4:45 in the morning, prima-facie, indicates brazen violation of Article 21 of the Constitution of India."
Then, the Court directed the Principal Commissioner, GST, who authorized the arrest of the petitioner, as well as the Officer who arrested the petitioner, to remain present before the Court at 02:00 PM on the same day in the post-lunch session.
Subsequently, the Officer who arrested the Petitioner tried to justify their actions, to which the Court observed that the replies were evasive.
The Court noted, "In the facts of the case, we find the action of the respondents department to be a brazen act of highhandedness where the constitutional safeguards available to a citizen have not been adhered to. As has already been noticed by us in the pre lunch session, the firm had already approached this Court challenging the attachment of its bank account on the ground that no show cause notice was issued and opportunity of personal hearing was denied."
The Court also impleaded Sugrive Meena, Principal Commissioner, CGST, Commissionerate, Ludhiana, and Mohmad Saleem, SIO, CGST, Commissionerate, Ludhiana, as respondents.
The Court concluded that the action of the Respondents was prima facie violative of Article 21 of the Constitution of India, and directed the Chief Judicial Magistrate, Ludhiana, to forthwith release the petitioner.
Accordingly, the Court listed the matter for a further date.
Cause Title: Kuldeep Goyal vs. Union of India and others [CWP-31964-2026 (O&M)]
Appearances:
Petitioner: Senior Advocate N.S. Boparai, Advocates J.S. Bedi, Aakriti and Umang Goyal.
Respondents: Senior Standing Counsel Sourabh Goel, Standing Counsel Naman Jain and Advocate Himanshi Gautam.