

Importer Cannot Escape Liability For Customs Agent's Fraud Or Claim Bona Fide Purchaser Defence For Forged Duty Scrips: Delhi High Court
The Court while upholding duty evasion findings against Paper Importers, rejected 'bona fide purchaser' defense, and held that beneficiaries liable to verify validity of EDI records used for duty exemptions.

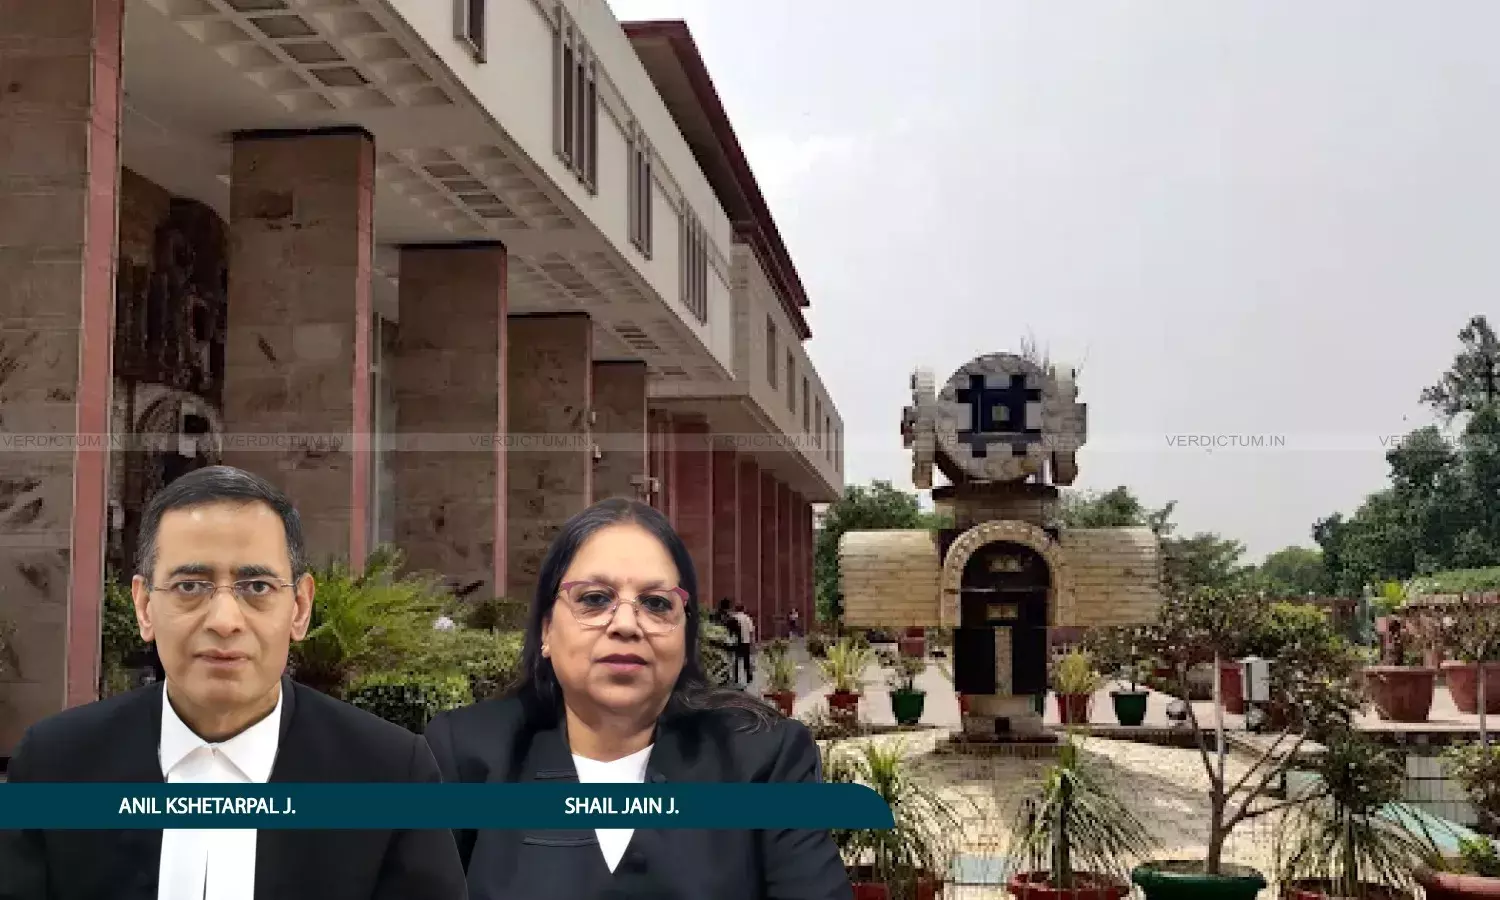
Justice Anil Kshetarpal, Justice Shail Jain, Delhi High Court
The Delhi High Court in a batch of 47 appeals and petitions, has held that an importer, as the ultimate beneficiary of customs duty benefits, bears the primary duty to verify the genuineness and lawful entitlement of duty credit scrips used for clearance of goods. The Division Bench ruled that importers cannot escape liability for duty evasion or forged instruments by pleading ignorance or attributing full responsibility to their customs clearing agents.
Dismissing the importers' plea of being innocent purchasers, the Court clarified that the protection afforded to a bona fide purchaser under civil property laws does not extend to statutory duty liabilities incurred through manipulated records in the Customs Electronic Data Interchange (EDI) system. The Court affirmed that an unauthorized enhancement of entitlement in official systems confers no valid right under the doctrine of nemo dat quod non habet.
A Division Bench comprising Justice Anil Kshetarpal and Justice Shail Jain observed, “…Since the fraudulent/forged/manipulated scrips were utilised for clearance of goods imported by the Appellant, the responsibility to verify the genuineness, validity and lawful entitlement of such scrips rested upon the Appellant, being the importer and the ultimate beneficiary of the duty benefit, which it failed to do… Having failed to exercise reasonable care to ascertain the genuineness and extent of the scrip entitlement, and having furnished incorrect declarations under the Act of 1962, the Appellant cannot claim protection as a bona fide purchaser or avoid the consequences arising from utilisation of the excess entitlement”.
Senior Advocate Kamal Mehta appeared for the appellant and Advocate Vikrant Nilesh Goyal appeared for the respondent.
“The plea of absence of direct knowledge regarding the actual manipulation of the EDI records, at the highest, may have relevant while examining the degree of culpability. However, penalty under Section 114A of the Act of 1962 does not require that the importer must personally execute such fraudulent act. Where the duty benefit has been obtained by suppression of material facts, wilful misstatement or fraudulent reliance upon an invalid entitlement, the statutory consequences necessarily follow”, the Bench further noted.
Between 2011 and 2015, various importers engaged in importing paper and paper-based articles utilized duty credit scrips issued by the Directorate General of Foreign Trade (DGFT) to discharge their customs duty liabilities. Investigations conducted by the customs authorities revealed that digital records within the Customs EDI system at the Inland Container Depot (ICD), Tughlakabad, were unlawfully manipulated.
Unauthorized individuals accessed the EDI system to artificially inflate scrip values, register non-existent scrips, and re-register already exhausted scrips multiple times. The importers authorized an entity, M/s Zealous International (through proprietor Sharafat Hussain), to handle their customs clearances using these manipulated scrips.
Following the investigation, the Customs Department issued show cause notices invoking extended periods of limitation under Section 28(4) of the Customs Act, 1962, demanding unpaid customs duty along with interest and imposing penalties under Sections 112, 114A, and 114AA. The Principal Commissioner of Customs confirmed the duty demands and penalties. On appeal, the Customs, Excise and Service Tax Appellate Tribunal (CESTAT), Delhi, upheld the duty demands and Section 114A penalties while setting aside certain personal penalties. The importers subsequently challenged the CESTAT orders through a batch of customs appeals and writ petitions before the High Court of Delhi.
Addressing the plea of bona fide purchase under Section 41 of the Transfer of Property Act, 1882, the Court rejected its application to statutory tax liability, holding that an invalid or manipulated scrip is void ab initio and cannot transfer a better title or legal entitlement than what was validly granted by the DGFT. Regarding statutory penalties, the Bench clarified that penalty under Section 114A of the Customs Act does not require direct personal participation by the importer in the fraudulent act; rather, statutory consequences follow automatically where duty benefit is obtained through non-disclosure or reliance on invalid entitlements.
The Court upheld the confirmation of customs duty demands along with applicable interest under Section 28(4) and Section 28AA of the Customs Act, 1962. It also affirmed the imposition of mandatory penalty under Section 114A of the Act. However, relying on the last proviso to Section 114A, the Court held that separate penalties under Section 112 or Section 114 cannot be levied simultaneously when a penalty under Section 114A is imposed. The batch of appeals and writ petitions were disposed of accordingly.
“The plea of absence of direct knowledge regarding the actual manipulation of the EDI records, at the highest, may have relevant while examining the degree of culpability. However, penalty under Section 114A of the Act of 1962 does not require that the importer must personally execute such fraudulent act. Where the duty benefit has been obtained by suppression of material facts, wilful misstatement or fraudulent reliance upon an invalid entitlement, the statutory consequences necessarily follow”, it noted.
Cause Title: M/s Raja Ram & Company v. Principal Commissioner of Customs (Import) (Neutral Citation: 2026:DHC:6920-DB)
Appearances:
Appellants: Kamal Mehta, Senior Advocate, Dr Sushil Kumar Gupta, Anshika Kumari, Advocates.
Respondents: Vikrant Nilesh Goyal, Inderpreet Singh, Kunal Dixit, Gibran Naushad, SSC.