
Assessing Officer Didn't Understand Basics Of Accounting: Delhi High Court Quashes Income Tax Demand Of ₹3.9 Crore On Cook
The Delhi High Court was considering a petition filed by the petitioner who had allegedly fallen prey to the fraud of misuse of his Permanent Account Number.
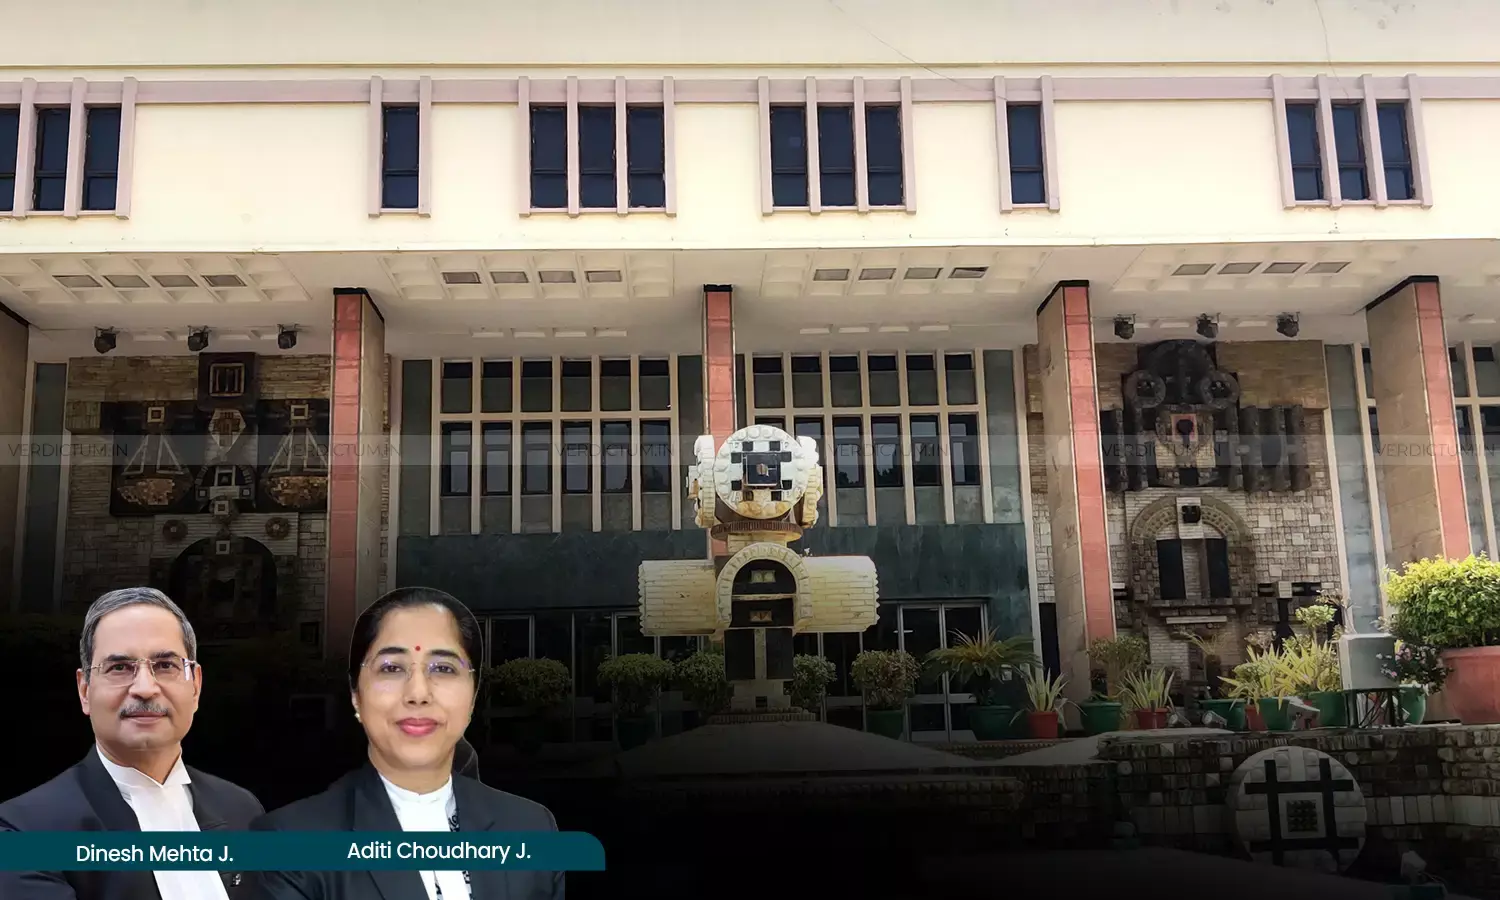
While observing that the eyes of an Assessing Officer should be sharp to pierce through the fraud, they should not slip away from the facts, the Delhi High Court has set aside an Income Tax assessment order of Rs 3.91 crore raised against a cook. Taking note of the order passed by the officer who handled the matter, the Bench stated that the same reflected the manner in which an assessing officer can agonise an assessee.
The High Court was considering a petition filed by the petitioner who had fallen prey to the fraud of misuse of his Permanent Account Number.
The Bench comprising Justice Dinesh Mehta and Justice Aditi Choudhary held, “This approach of the AO reveals that he has not even cared to understand the nature of transaction –either he did not understand the basics of accounting or he did not want to. It has resulted in demand against the petitioner being twofold. Though the order in toto is wholly void and without jurisdiction inasmuch as the transactions did not relate to the petitioner, but we have analysed the same in order to show the manner in which an assessing officer can agonise an assessee.”
“A Tax Enforcement Officer should strive to achieve high revenue target but he should keep his feet firmly grounded on the floor of reality. His eyes should be sharp to pierce through the fraud but they should not slip away from the facts”, it added.
Advocate A.K. Babbar represented the Petitioner while Senior Standing Counsel Gaurav Gupta represented the Respondent.
Factual Background
The petitioner claimed to have obtained a Permanent Account Number out of anxiety to secure an identity proof issued by the government, though his income was never taxable. The petitioner was working as a small contractual employee either as a security guard or as a cook at the relevant time. As per the facts pleaded before the AO, the Petitioner worked as a cook. The petitioner came to receive a notice under Section 148A(b) of the Income Tax Act, 1961, alleging that as per the Risk Management Strategy formulated by CBDT, the Petitioner (assessee) had made a cash payment to Montage Enterprises Pvt. Ltd. of Rs.24,86,63,500. The notice also showed a cash sale of Rs.24,62,01,485 under Permanent Account Number.
The petitioner then proceeded to file a police complaint but said complaints bore no fruit. The petitioner filed a reply to the aforesaid notice and asserted that he had earned no taxable income, had not entered into any transaction mentioned in the notice and that somebody had misused his PAN details. Apart from raising the demand of about Rs. 3,91,06,511, the Assessing Officer had also recorded satisfaction to initiate penalty proceedings against the petitioner for misreporting of income; non-compliance of the statutory notice, non-maintenance of books of account and for failure to get the books of account audited.
Reasoning
The Bench was of the view that the petitioner could not be relegated to avail the remedy of appeal against a huge demand of Rs 3,91,06,511 given his financial status. “Even if his entire demand is stayed by the appellate authority. At the least he would be expected to furnish surety which we are sure, he would be unable to furnish–the remedy of appeal would, therefore, be illusory and inefficacious”, it added.
The Bench further clarified, “A demand of about Rs. 3.91 crore, slapped against a person with no means, that too on the strength of portal data alone, without an answer to his request for particulars, exposes him to recovery proceedings, accrual of interest and penalty proceedings that he cannot meet or contest on the terms the statute lays down. Such a liability is not a neutral fiscal event for him, it results into a continuing cause of anxiety, constant fear of coercive recovery and complete loss of mental peace. That is an additional reason, along with the breach of Article 14 and the inefficacy of the appellate remedy, why we do not relegate him to the statutory forum.”
On a perusal of the facts of the case, the Bench found that the assessment order was founded solely on the limbs of information available on risk management strategy or Form 26AS and no independent inquiry has been conducted by the AO. The Bench found substance in the petitioner’s stand that during the relevant period he was engaged as a contractual employee as a security guard/cook and according to the Bench, there was every reason to accept that he had no nexus with the transactions mentioned in the assessment order.
Thus, holding that the huge demand of Rs 3.91 crore was nothing short of a threat to his mental and emotional health, the Bench allowed the appeal and quashed the assessment order.
Cause Title: Lalit v. Union Of India (Neutral Citation: 2026:DHC:9012-DB)
Appearance
Petitioner: Advocate A.K. Babbar
Respondent: Senior Standing Counsel Gaurav Gupta, Jr. Standing Counsels Shivendra Singh, Yojit Pareek, SPC Vedansh Anand, Govt Pleader Shivam Kumar