

Deliver Decision Within 90 Days In Matters Closed For Judgment: Bombay High Court Asks Income Tax Appellate Tribunals
The Bombay High Court reprimanded the Appellate Tribunal for its delay in pronouncing judgment in a matter where the appeal was argued on the third occasion.

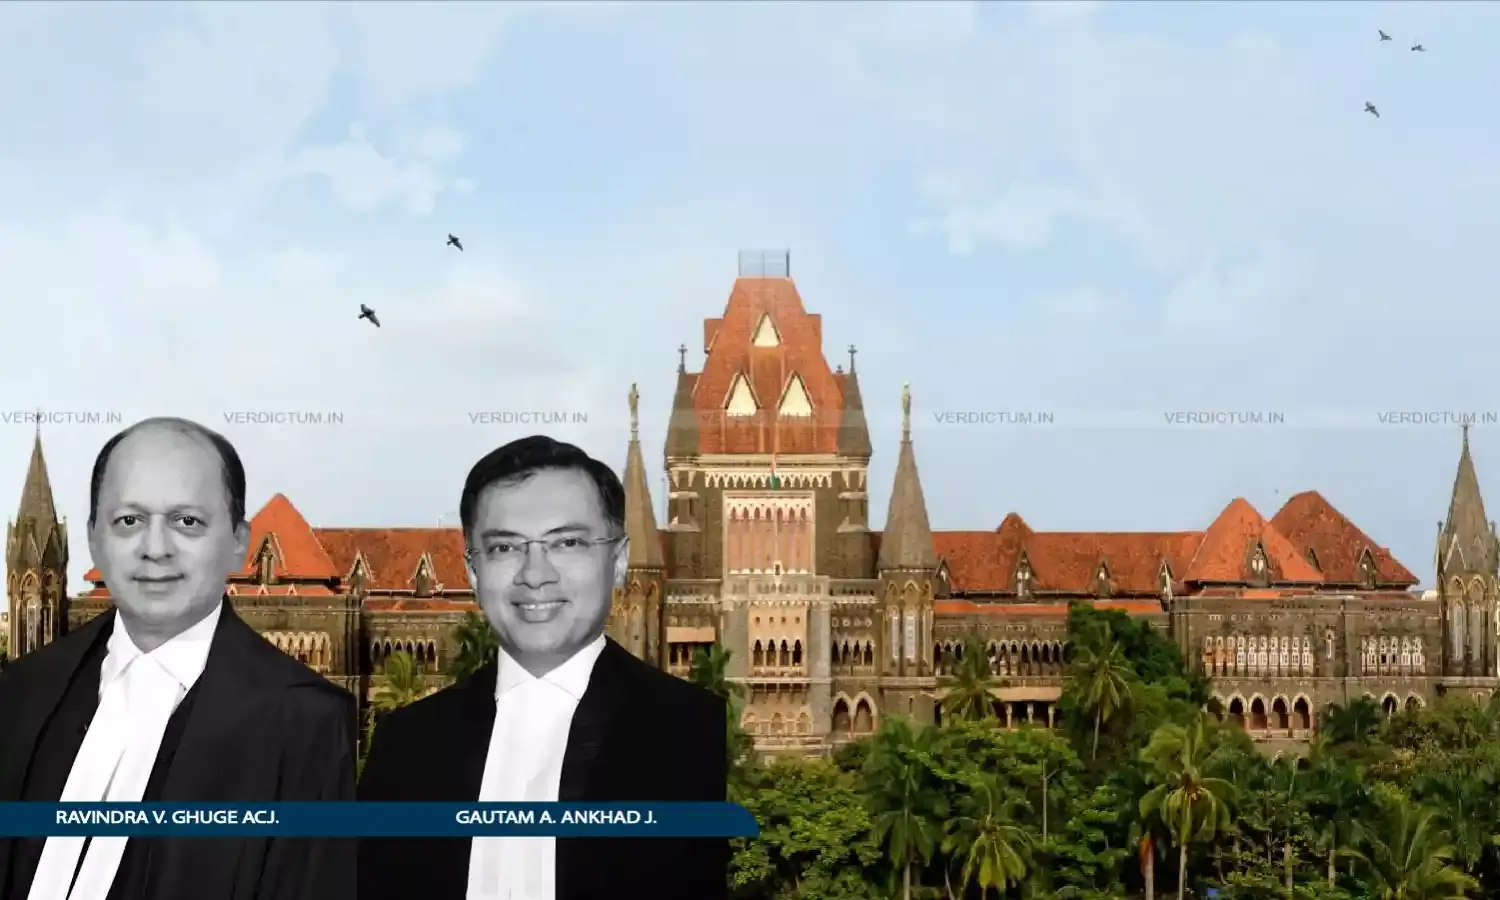
The Bombay High Court has reprimanded the Income Tax Appellate Tribunal for its delay in pronouncing judgment in a matter where the appeal was argued on the third occasion. Directing all the Income Tax Appellate Tribunals to scrupulously follow Rule 34 of the Income Tax (Appellate Tribunal) Rules, 1963, the Bench further held that the decision shall be delivered on or before the 90th day by the concerned Bench in exceptional circumstances for matters closed for judgment.
The High Court was considering a petition concerning Rule 34 of the Income Tax (Appellate Tribunal) Rules, 1963, which pertains to ‘order to be pronounced, signed and dated’.
The Bench of Acting Chief Justice Ravindra V. Ghuge and Justice Gautam A. Ankhad held, “We direct that all the Income Tax Appellate Tribunals shall scrupulously follow Rule 34 and ensure that matters which are heard and closed for Judgment, shall also mention the date for pronouncement which shall be within the period of 60 days. A judgment should be delivered within the said period. If on account of exceptional circumstances or extra-ordinary reasons justifying further time being required by the Tribunal, the judgment shall be delivered on or before the 90th day by the concerned Bench.”
Advocate Dhruv Janssen Sanghavi represented the Petitioner while Advocate Subir Kumar represented the Respondent.
Factual Background
A Bench of the Appellate Tribunal at Mumbai heard an appeal. The matter was closed for judgment on July 1, 2025. It was the case of the petitioner that as per Rule 34 sub-rule 5(c), the judgment should have been delivered within 60 days, and only in exceptional and extraordinary circumstances, within a further period of 30 days. Since this was not done by the Tribunal, the Appeal was released on October 7, 2025. The Appeal then came up before the new composition of the Bench. However, the judgment was not delivered, and the matter was released on February 27, 2026, after 90 days.
The Petitioner thus approached the High Court annoyed by the two hearings caused in the matter, which did not fetch any result. The said Appeal is to be heard by the Tribunal (Coram: Judicial Member Beena Pillai and Accountant Member Arun Khopdia), which is reserved on May 13, 2026. The 90-day period is to expire on August 13, 2026.
Reasoning
The Bench took note of the fact that the Petitioner was apprehensive that if the matter was not decided, the Petitioner would have to re-argue before the Tribunal for the fourth time. It was brought to the Court’s notice that there were instances when the matters had been closed and released on 3 or 4 occasions.
The Bench thus stated, “Our judicial conscience is shocked by the above stated information. It cannot be countenanced that a matter closed for judgment, is released without a judgment even when Rule 34 mandates a decision within 90 days. How far would the litigants tolerate the rigours of litigation, when a Appeal is released on multiple occasions. In the present case, the Appeal has been finally argued on the 3rd occasion, and the time-line is to expire shortly. We have taken a serious note of this aspect.”
Thus, partly allowing the appeal, the Bench asked the Appellate Tribunal to ensure that the judgment in the Petitioner’s case is delivered on or before August 13, 2026.
The Bench concluded the matter by directing the Income Tax Appellate Tribunals to ensure that matters which are heard and closed for judgment, the decision sould be delivered on or before the 90th day by the concerned Bench.
Cause Title: Rajesh R. Hemrajani v. Income Tax Appellate Tribunal & Anr. (Case No.: Writ Petition (L) No. 10271 of 2026)
Appearance
Petitioner: Advocates Dhruv Janssen Sanghavi, Anirudh Srinivasan, Prajyot Sawardekar
Respondent: Advocates Subir Kumar, Ashita Aggarwal