
Date Of Import Under Foreign Trade Policy Must Be Reckoned From Shipment Date, Not Customs Clearance Date: Bombay High Court
The Court held that Customs authorities could not apply a later restriction merely because the bills of entry were filed after the notification, even though the goods had already been dispatched and arrived in India before publication.
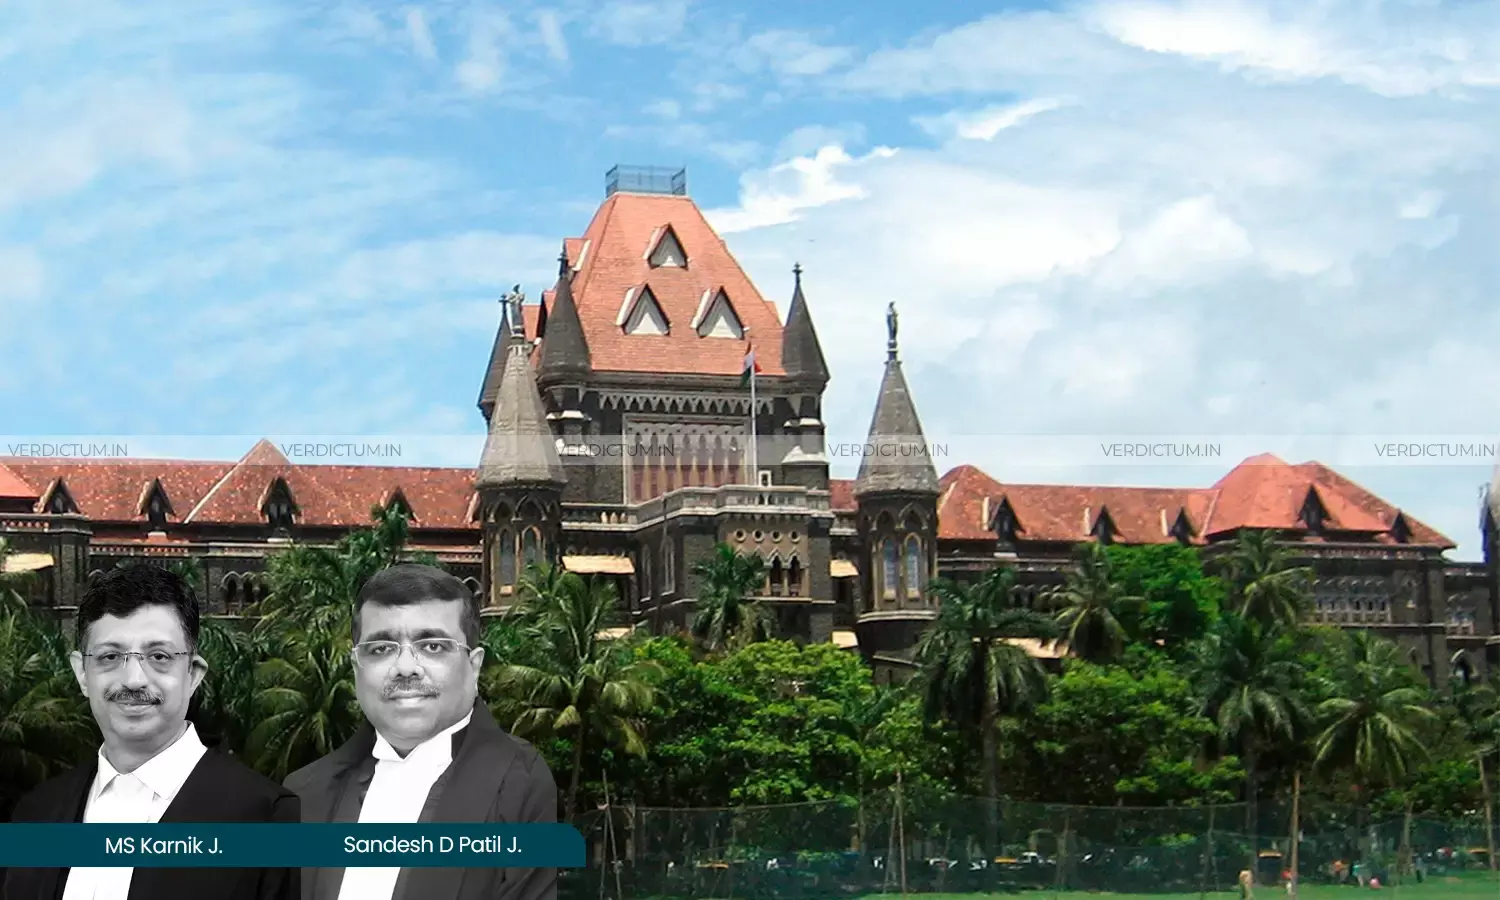
The Bombay High Court held that the date of import under the Foreign Trade Policy is determined by the shipment or dispatch documents specified in the applicable policy and Handbook of Procedures, not the date the goods cross the customs barrier.
The High Court directed the release of studded platinum jewellery imported before a notification changed its status from “free” to “restricted”.
The Court was hearing a writ petition challenging Customs authorities’ communications refusing clearance of three consignments under Notification No. 02/2026-27, which amended the import policy for goods falling under CTH 7113.
A Bench of Justice M.S. Karnik and Justice Sandesh D. Patil observed: “It is pertinent to refer to paragraph 2.17(a) read with paragraph 11.11 of the Handbook of Procedure, 2023 (“HBP”) for the purpose of FTP, which indicates that the date of reckoning of import is to be decided with reference to the date of shipment/dispatch of goods from the supplying country and not the date of arrival of goods at an Indian port or on the date of clearance for home consumption”.
The Bench further added: “It would therefore be clear that for the purpose of Customs Act, the import would be completed when the goods cross the customs barriers and not the day on which the goods had landed in India. On the other hand, for the purpose of reckoning the date of import for applicability of the provisions of FTP is specified in paragraph 1.05(b) of the FTP read with paragraph 2.17 read with paragraph 11.11 of HBP. Paragraph 1.5 (b) of FTP clearly provides that the date of import/export is defined in paragraph 2.17 of HBP. Bill of Lading or shipping bill are key documents for deciding the date of import and export respectively.”
Senior Advocate Prakash Shah appeared for the petitioner. Advocate Maya Majumdar appeared for the Customs authorities, while Advocates Jitendra B. Mishra and Ashutosh Misra appeared for the Union of India and the Directorate General of Foreign Trade.
Background
Heimerle Refinery Private Limited imported studded platinum jewellery under five airway bills dated March 30 and 31, 2026. The goods arrived in India on April 1 and 2, before Notification No. 02/2026-27 was published in the e-Gazette on April 2.
The notification changed the import policy for the relevant goods from “free” to “restricted”. Although the goods had arrived earlier, the petitioner filed the disputed bills of entry after the notification’s publication.
The petitioner did not challenge the Central Government’s power to amend the Foreign Trade Policy or the notification’s validity. It contended only that the restriction could not apply to goods already imported under the earlier policy.
The authorities argued that the goods remained pending for home-consumption clearance when the restriction took effect. They contended that the notification applied immediately, excluded transitional benefits and operated irrespective of previous contracts or shipment status.
Court’s Observations
Foreign Trade Policy Supplies Its Own Date Of Import
The Court observed that paragraph 1.05(b) of the Foreign Trade Policy expressly made the policy prevailing on the date of import applicable. That date was defined through paragraph 2.17 of the Handbook of Procedures, read with paragraph 11.11.
The Bench noted that paragraph 2.17 reckoned import from the date of shipment or dispatch from the supplying country, rather than arrival at an Indian port or clearance for home consumption. For air imports, paragraph 11.11 treated the relevant airway bill date as the shipment date, provided it represented when the goods left the last airport in the exporting country.
The Court stated: “In the present case, admittedly the Bill of Lading and Shipping Bill are the key documents which indicate the date of import and export respectively which is well before the change of policy from ‘free’ to ‘restricted/prohibited/state trading’ or ‘otherwise regulated’. Thus, the import/export was already made before the date of such regulation/restriction. In our view and as rightly submitted by Mr. Shah, learned Senior Advocate, once the date of import is defined under the FTP, it is not open for the respondents to take recourse to the date of import under the Customs Act. The goods were shipped in terms of the policy.”
The Court clarified that adopting the Customs Act conception of import for applying the Foreign Trade Policy would make the policy’s express definition redundant and meaningless.
Filing Of Bills Of Entry Was Irrelevant To The Policy Change
The Court rejected the authorities’ contention that filing or assessment of the bills of entry after the restriction made the notification applicable.
The Bench explained that Section 15 of the Customs Act makes the bill-of-entry date relevant for determining the rate of customs duty. The present dispute, however, concerned the policy governing importability, not any change in the rate of duty.
The Court held: “In our view, the date of filing bills of entry or its clearance/out-of-charge post the restriction is wholly irrelevant and alien to the applicability of a change in the FTP. In terms of Section 15 of the Customs Act, the date of filing of bills of entry is relevant for the rate of duty of customs and, in the present case, the rate of duty is the same prior to and post the Notification.”
The Bench distinguished Union of India v. Ganesh Das Bhojraj (2000) and Kiran Spinning Mills v. Collector of Customs (1999). It observed that those decisions concerned the applicable rate of duty under the Customs Act, not the date of import under the Foreign Trade Policy.
Restriction Could Not Apply Before Notification’s Publication
The Court relied on Viraj Impex Private Limited v. Union of India (2026), which followed Union of India v. G.S. Chatha Rice Mills (2020), to hold that a notification acquires legal force only upon publication in the Official Gazette. In an electronic gazette, the precise time of upload determines when it takes effect.
The Court stated: “Thus in view of what has been held by Their Lordships, we have no hesitation in holding that the Notification acquired the force of law only on 2nd April 2026 at 20:52:58 hours, and it can be validly applied only to the goods dispatched from the country of export after its publication and not to goods already dispatched and arrived in India prior to its publication.”
The Bench also followed Enero Jewels Private Limited v. Union of India (2026) and Bright Metal Refiners v. Director General, Directorate General of Foreign Trade (2026), where goods imported before the notification were permitted clearance despite bills of entry being filed later.
DGFT Clarification Could Not Override The Policy
The Court rejected reliance on a subsequent DGFT Office Memorandum stating that consignments not cleared before April 1 would be governed by the restricted policy irrespective of their arrival date.
The Bench held that the memorandum lacked statutory force and could not amend or override the definition of “date of import” contained in the Foreign Trade Policy and Handbook.
The Court observed: “The said OM has no statutory force and cannot override the FTP. The OM is not even subordinate legislation and no authority of law is pointed out in exercise of which the said OM is issued.”
Referring to Commissioner of Central Excise v. Ratan Melting and Wire Industries (2008) and Director General of Foreign Trade v. Kanak Exports (2015), the Court held that an executive clarification could not retrospectively alter the statutory policy framework.
Conclusion
The Court allowed the writ petition and declared that Notification No. 02/2026-27 did not apply to goods that had arrived in India before its publication on April 2, 2026.
It directed the authorities to expeditiously release the consignments covered by the three disputed bills of entry and permit submission of one bill of entry without insisting upon an import authorisation or licence. The connected interim application was also disposed of.
Cause Title: Heimerle Refinery Private Limited v. Union of India and Others (Neutral Citation: 2026:BHC-OS:22729-DB)
Appearances
Petitioner: Senior Advocate Prakash Shah with Advocates Jas Sanghavi and Linzy Sharan, instructed by PDS Legal
Respondents: Advocates Maya Majumdar and Abhishek R. Mishra; Advocates Jitendra B. Mishra and Ashutosh Misra